Credit Card Calculator
Last updated: 27 June 2026
Reviewed by Gavin Meiring, Lead research and primary author · Doctoral Candidate (Corporate Governance) · Research and drafting assisted by AI
- If you only make minimum payments on a $3,000 credit card balance at 24% APR, it will take over 27 years to pay off and cost you $5,000+ in interest.
- The first credit card — the BankAmericard — was mailed unsolicited to 60,000 people in Fresno, California in 1958. Congress eventually banned the practice.
- Americans collectively carry around $1 trillion in credit card debt, at an average interest rate of about 21% — the highest on record.
Credit Card Calculator
A credit card calculator shows how long it will take to pay off a balance and how much interest you will pay in total, based on your outstanding balance, interest rate, and monthly payment. It is used by cardholders who want to understand the real cost of carrying a balance and to plan faster repayment.
How to Use the Credit Card Calculator
- Enter your current credit card balance.
- Enter the annual percentage rate (APR) on your card.
- Enter your planned monthly payment amount.
- Click calculate to see the number of months to pay off the balance and the total interest paid.
- Try increasing the monthly payment to see how much interest and time you save.
The Formula
Each month, interest is applied to the outstanding balance before the payment is deducted:
Monthly interest rate: r = APR / 12 / 100
Interest charged this month = Balance x r
Remaining balance after payment = Balance + Interest - Monthly Payment
This repeats until the balance reaches zero. The minimum payment on most UK credit cards is 1 to 3% of the outstanding balance or a fixed minimum (often £25), whichever is greater. If your payment is lower than the monthly interest charge, the balance will grow rather than shrink.
Real-World Example
You have a £3,000 balance on a card with a 21.9% APR. You pay £80 per month.
- Monthly rate: 21.9% / 12 = 1.825%
- Month 1 interest: £3,000 x 0.01825 = £54.75
- Balance after payment: £3,000 + £54.75 - £80 = £2,974.75
At this rate, it takes 64 months to clear the balance, which is five years and four months. Total interest paid: £2,101.24, so the £3,000 costs £5,101.24 in all.
If you increase the payment to £150 per month:
- Time to clear: 26 months
- Total interest: £766.67
Raising the payment from £80 to £150 cuts the interest bill by £1,334.57 and saves 38 months.
The Hidden Cost of Minimum Payments
Making only the minimum payment each month is one of the most expensive ways to manage credit card debt. On a £3,000 balance at 21.9% APR, paying only the minimum (which reduces as the balance falls) could take over 20 years to pay off completely and cost more than £3,000 in interest, effectively doubling the cost of whatever you bought. Card issuers are legally required to show a "minimum payment warning" on statements that illustrates this cost. Use this calculator to set a fixed payment that clears your balance within a realistic timeframe, such as 12 to 24 months, and treat it as a non-negotiable monthly commitment.
Reference Table: How long a $5,000 card balance takes to clear
Months to clear a $5,000 balance paying a percentage of the balance each month, with a $25 floor. At 19.9% the 2% minimum takes 513 months and the 3% minimum takes 182. At 22.9% and 26.9% the 2% payment does not clear the balance inside the calculator's 1,200-month ceiling, because 2% of the balance sits close to the monthly interest and the debt creeps down while the interest compounds. Paying a fixed amount instead of a percentage clears the balance far sooner.
| APR | At 2% minimum | At 3% minimum | Interest to the 1,200-month ceiling (2% path) |
|---|---|---|---|
| 19.9% | 513 months | 182 months | $19,637 |
| 22.9% | 1,200 months, ceiling | 217 months | $69,460 |
| 26.9% | 1,200 months, ceiling | 298 months | $793,581 |
Worked Example on Screen
The capture below shows Credit Card Calculator after the inputs were entered, with the result on screen. Enter the same values to reproduce it.
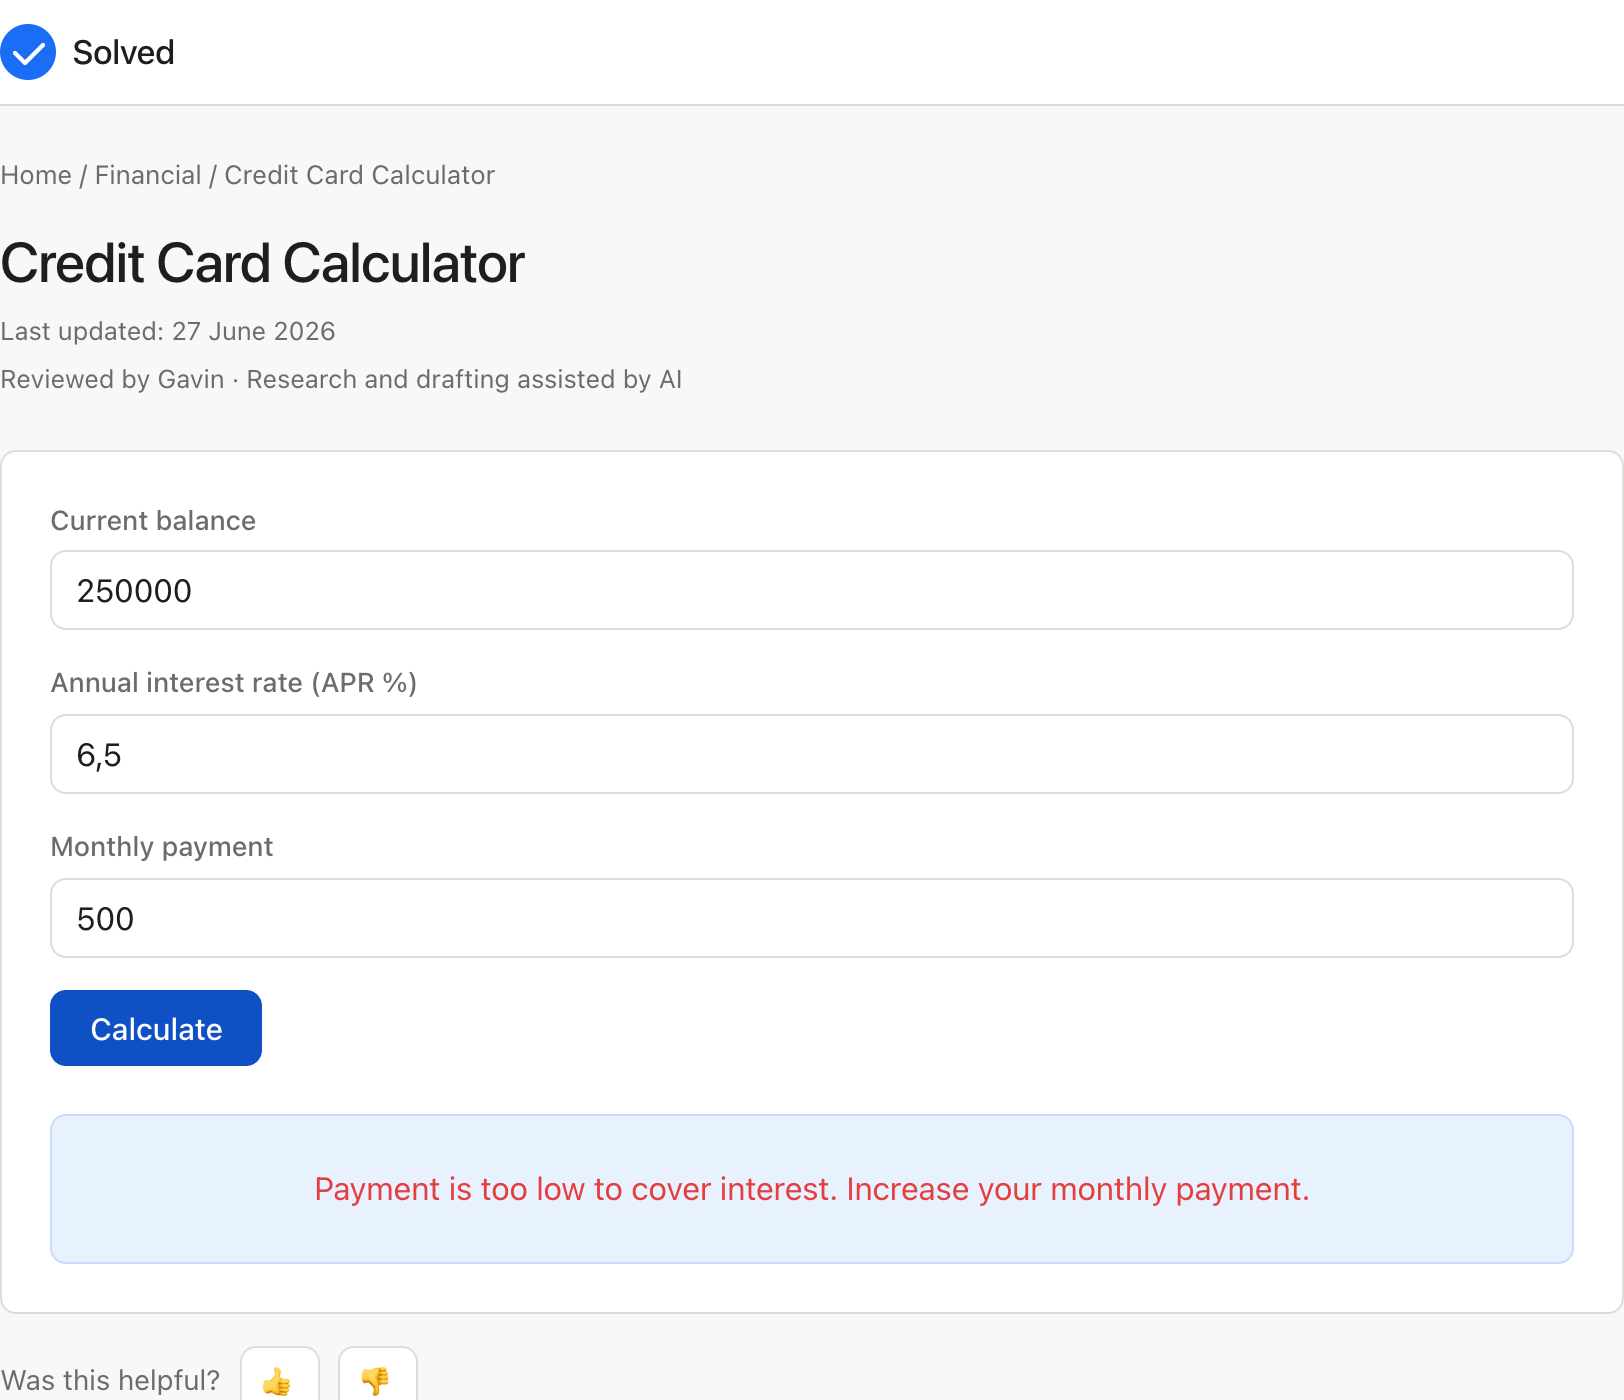
Captured from solved.tools on 10 September 2026.
Payment Ladder on a £3,000 Balance
The example above uses a £80 payment. The table below prices the same balance at six payment levels, so the trade between a higher payment and a shorter, cheaper debt sits in one place.
| Monthly payment | Months to clear | Total interest | Total paid |
|---|---|---|---|
| £80 | 64 | £2,101.24 | £5,101.24 |
| £100 | 44 | £1,384.67 | £4,384.67 |
| £125 | 32 | £982.98 | £3,982.98 |
| £150 | 26 | £766.67 | £3,766.67 |
| £200 | 18 | £537.60 | £3,537.60 |
| £250 | 14 | £417.33 | £3,417.33 |
Balance £3,000 at an APR of 21.9%, interest added before each payment, no new spending on the card. Each row was run through the calculator's own month-by-month loop.
At £80 the payment clears the £54.75 of interest the first month carries by £25, so the balance falls slowly and the debt runs for five years and four months. Raising the payment to £150 removes 38 months and £1,334.57 of interest. The step from £150 to £250 saves a further £349.34 and 12 months. The first £70 of extra payment buys far more than the last £100 does.
How the Ladder Was Calculated
Every month, interest is the outstanding balance multiplied by the APR divided by 12, and the payment is taken after the interest is added. The loop ends when the balance reaches zero. The calculator stops at 1,200 months, so a payment that only clears the monthly interest is reported as a ceiling rather than a payoff date.
The model assumes a fixed APR for the whole term, no new purchases, no annual fee, no penalty charges, and a payment made on time every month. A promotional rate that expires, a late payment fee or one extra purchase all push the payoff out. The figures are the best case for the payment you entered.
Frequently Asked Questions
What does APR mean on a credit card? APR stands for Annual Percentage Rate. It represents the yearly cost of borrowing, expressed as a percentage, and includes the interest rate plus any standard fees. For credit cards with no annual fee, the APR and the interest rate are usually the same. Credit card APRs in the UK typically range from about 18% to over 40%, depending on the card and the applicant's credit history.
Does paying the minimum harm my credit score? Paying the minimum on time keeps your account in good standing and avoids missed payment markers. However, a high credit utilisation ratio (your balance relative to your credit limit) can lower your score. Keeping utilisation below 30% of your limit and paying as much as possible each month benefits both your credit score and your finances.
Should I transfer my balance to a 0% card? A 0% balance transfer card can eliminate interest charges for an introductory period, typically 12 to 30 months, allowing every payment to reduce the principal. There is usually a balance transfer fee of 2 to 3%. Use this calculator to check whether the fee is lower than the interest you would otherwise pay during the 0% period. Aim to clear the balance before the 0% period ends.
What happens if I miss a credit card payment? Missing a payment typically triggers a late fee (around £12), increases your APR on some cards, and adds a missed payment marker to your credit file, which stays for six years. Set up a direct debit for at least the minimum payment each month to prevent accidental missed payments, then manually pay more when you can.
Also try these free tools:
Extended Reference Notes
The notes below cover the broader context that informs how to use the Credit Card Calculator well.
Typical Input Ranges
Most real-world uses of the Credit Card Calculator fall into a middle band where the result is stable and useful. Very small inputs to the Credit Card Calculator often round to zero or near-zero, and very large inputs amplify every rounding error in the calculation. The middle band, where the Credit Card Calculator inputs are ordinary sizes, is where the tool is most reliable.
Assumptions Behind the Formula
The Credit Card Calculator assumes the inputs stay fixed across the period or scenario being modelled. Rates move, values change, and fees appear, so treat the Credit Card Calculator output as a clean reference and layer in the frictions your own situation adds.
Common Edge Cases
Three situations change the Credit Card Calculator answer in ways the formula does not surface: boundary values near zero, rounding cascades across many steps, and unit mismatches between fields. When any of these apply, sanity-check the Credit Card Calculator result against an independent estimate.
When to Revisit the Calculation
The Credit Card Calculator output is only as current as its inputs, so re-run the calculation whenever a key value changes materially. A quarterly re-check of the Credit Card Calculator suits personal planning; monthly suits active business or investment decisions.
Relationship to Other Tools
The Credit Card Calculator shares inputs and outputs with the other tools in its category. If the same numbers feed several tools, capture them once and run each tool so the comparison stays consistent with the Credit Card Calculator.
Practical Checklist Before Relying on the Result
Before acting on the Credit Card Calculator output, run a short mental checklist: inputs in the right units, direction of the result matching intuition, and magnitude plausible. Each check takes seconds and catches the most common classes of Credit Card Calculator error before they reach a decision.
Putting the Result to Work
A single Credit Card Calculator run usually narrows the range of plausible answers rather than settling the question. Compare the Credit Card Calculator result against a benchmark or a previous run, and ask what would have to change for the answer to flip a decision.
Sensitivity to Inputs
Some inputs move the Credit Card Calculator result more than others; changing each by a small amount shows which ones matter. Spend the effort on the high-impact Credit Card Calculator inputs and treat the low-impact ones as approximate.
A Note on Stale Inputs
A calculation is only as fresh as the inputs that feed it, so note the date the Credit Card Calculator inputs were last refreshed. A six-month-old Credit Card Calculator result can be as wrong as a wrong calculation when the underlying values have moved on.