Loan Calculator
Last updated: 28 June 2026
Research and drafting assisted by AI.
- The concept of charging interest on loans dates back to ancient Mesopotamia around 3000 BC. Clay tablets record grain loans at 20% annual interest.
- Personal loan interest rates are typically 2–3x higher than mortgage rates because there's no collateral for lenders to reclaim if you default.
- The word 'bank' traces back to the Italian 'banca', meaning bench , the surface on which medieval money-changers conducted business in market squares.
Loan Calculator
A loan calculator works out your monthly repayment, total interest, and total cost for any fixed-term personal or business loan. It is useful for comparing offers from different lenders, understanding the true cost of borrowing, and deciding how much you can afford to repay each month.
How to Use the Loan Calculator
- Enter the loan amount you want to borrow.
- Enter the annual interest rate from your lender's quote.
- Set the loan term in months or years.
- Click calculate to see your monthly payment, total interest, and total amount repaid.
- Adjust the amount or term to find a repayment level that fits your budget.
The Formula
Loan repayments use the standard amortisation formula:
M = P x (r(1 + r)^n) / ((1 + r)^n - 1)
Where M is the monthly payment, P is the principal (the amount borrowed), r is the monthly interest rate (the annual rate divided by 12), and n is the number of monthly payments. Multiply M by n to get the total repaid, then subtract P to find total interest paid.
Real-World Example
You borrow $10,000 over 3 years (36 months) at an annual rate of 6.9%.
- Monthly rate: 6.9% / 12 = 0.575%, or 0.00575
- Number of payments: 36
- Monthly payment: 10,000 x (0.00575 x (1.00575)^36) / ((1.00575)^36 - 1)
- Result: approximately $308 per month
- Total repaid: $308 x 36 = $11,088
- Total interest paid: $1,088
The annual percentage rate (APR) you see in adverts may differ from the flat interest rate; always confirm which rate is being used when comparing loan offers.
Common Mistakes to Avoid
Many borrowers focus only on the monthly payment and overlook the total cost. A longer term lowers your monthly payment but increases the amount of interest you pay overall. For example, stretching a $10,000 loan from 3 to 5 years at the same rate reduces the monthly payment but adds several hundred dollars in interest. Also watch for arrangement fees, which some lenders add to the loan balance, meaning you pay interest on the fee itself. Always ask for the representative APR and total amount repayable before signing any agreement.
Reference Table: Monthly payment on a $25,000 personal loan
Five years at 10% costs $531 a month and $31,871 in total, against $29,040 over three years. The shorter term carries a higher payment and less interest.
| Rate | 3-year term | 5-year term | 7-year term |
|---|---|---|---|
| 6% | $761 | $483 | $365 |
| 8% | $783 | $507 | $390 |
| 10% | $807 | $531 | $415 |
| 12% | $830 | $556 | $441 |
Worked Example on Screen
The capture below shows Loan Calculator after the inputs were entered, with the result on screen. Enter the same values to reproduce it.
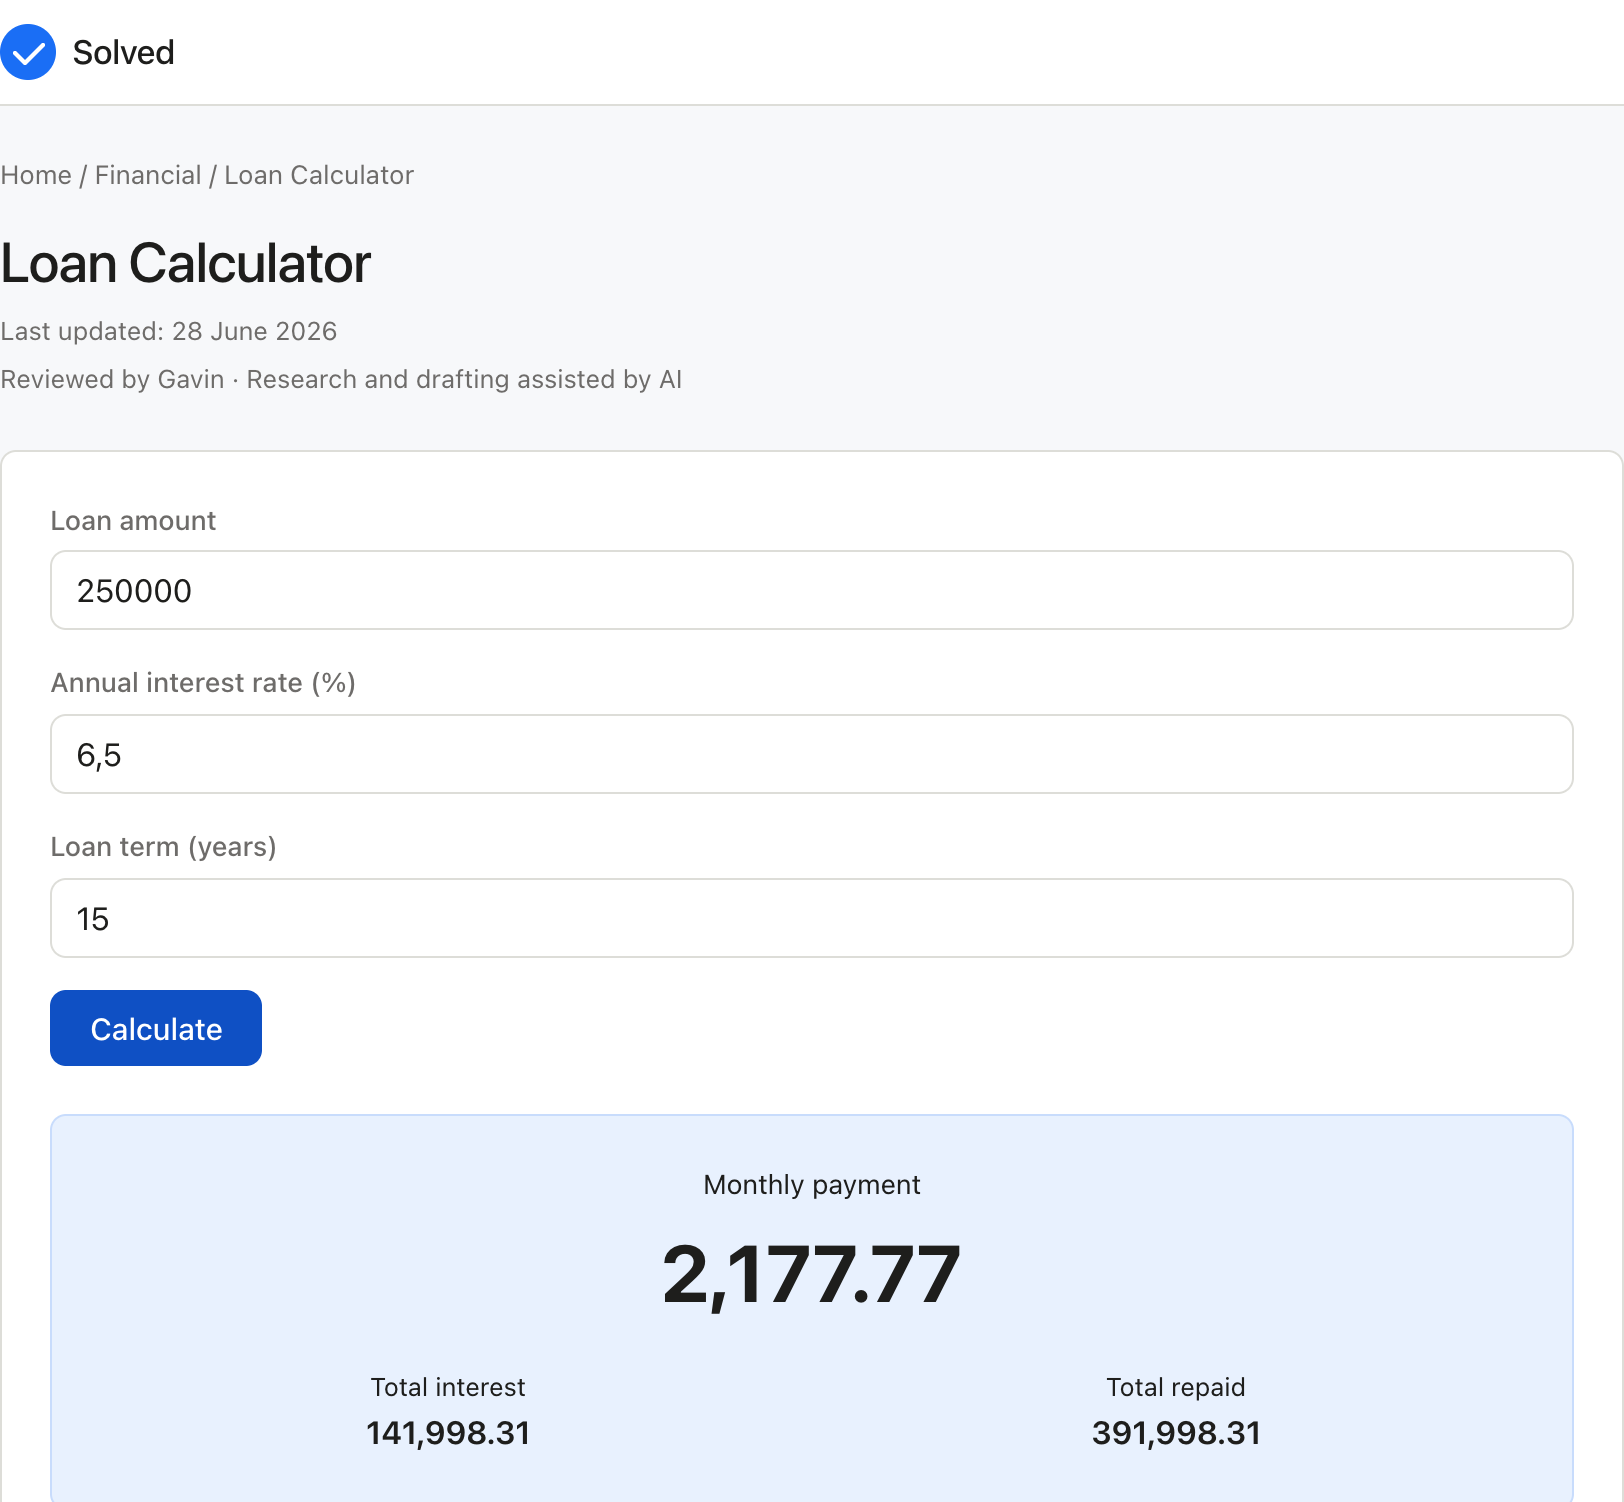
Captured from solved.tools on 10 September 2026.
Frequently Asked Questions
What is the difference between APR and the interest rate? The interest rate is the annual cost of borrowing expressed as a percentage of the loan. The APR (Annual Percentage Rate) includes the interest rate plus any mandatory fees, giving a more accurate picture of the total cost. Use APR when comparing different loan products, since it accounts for fees the advertised rate might not show.
Can I repay a loan early to save on interest? Yes, in most cases you can overpay or settle early, and doing so reduces the remaining interest. However, some lenders charge an early repayment fee of one to two months' interest. Check the terms before making extra payments to confirm the saving outweighs any penalty.
How does my credit score affect my loan rate? Lenders use your credit score to assess risk. A higher score typically qualifies you for lower rates. The representative APR shown in adverts only has to be offered to 51% of approved applicants, so your personal rate may be higher depending on your credit profile.
What is a secured versus an unsecured loan? A secured loan is tied to an asset, usually your home. If you fail to repay, the lender can claim that asset. Secured loans generally offer lower rates and higher borrowing limits but carry more risk. An unsecured loan requires no collateral, which makes it riskier for the lender and typically results in a higher interest rate.
What the Term Costs You in Total
The payment ladder above shows what the term does to the monthly figure. The total cost is the number that decides the deal, and it moves the other way.
| Rate | 3-year total cost | 5-year total cost | 7-year total cost |
|---|---|---|---|
| 6% | $27,380 | $28,999 | $30,678 |
| 8% | $28,203 | $30,415 | $32,731 |
| 10% | $29,040 | $31,871 | $34,862 |
| 12% | $29,893 | $33,367 | $37,071 |
On $25,000 at 10%, moving from a three-year term to a seven-year term saves $392 a month and costs $5,822 more in interest. That is the trade in one line. The payment falls because the balance stays open longer, and interest is charged on the balance for every month it is open. A shorter term is the cheaper loan, provided the higher payment fits your budget without strain.
What the Monthly Payment Is Made Of
Every payment splits between interest and principal, and the split changes month by month. On $25,000 at 10% over five years the payment is $531.18. In the first month, interest takes $208.33 and $322.84 comes off the balance. By month 24 the interest portion has fallen to $140.44 and the principal portion has risen to $390.74, because the balance it is charged on has fallen to $16,461.80. In the last month almost the whole payment is principal.
Two things follow from that. An overpayment early in the term is worth more than the same amount later, because the balance it removes would have attracted interest in every remaining month. And a fixed payment means a growing share of each payment works for you as the term runs, which is why total interest on a long loan is not the first month's interest multiplied by the number of months.
Fees, APR and the Rate in the Advert
The interest rate is the price of the money. The APR is that price plus the mandatory fees, expressed as one annual rate, which is why the APR is the figure to compare between offers. A $25,000 loan at 10% with a $500 arrangement fee added to the balance costs more than the same loan with the fee paid upfront, even though both quote 10% and the difference is interest charged on the fee for the whole term.
Check three things before signing. First, whether the fee is added to the balance or paid separately. Second, whether the rate is fixed or variable, and if variable, what it is tied to and how far it can move. Third, the total amount repayable, which is the figure that includes everything. A representative rate in an advertisement is a marketing figure rather than an offer, since it only has to be available to a stated share of approved applicants. Your own rate depends on your credit record, your income, and the term you pick.
When a Loan Is the Wrong Tool
A personal loan is a fixed-cost way to borrow a known amount for a known period. It suits a planned purchase with a known price and a repayment period you can see the end of. It is the wrong tool when the amount is uncertain, when the term would stretch past the life of the thing being bought, or when cheaper borrowing exists.
A credit card balance moved to a 0% balance transfer costs less than a loan at any rate in the table above, as long as the balance is cleared inside the promotional window and the transfer fee is small. Borrowing against a home is cheaper in rate terms and far more expensive in consequence, because the home secures the debt. Where an employer offers a salary advance or a family loan at no interest, the arithmetic beats every entry in the table.
Consolidating existing debt deserves particular care. If the debts being consolidated were a symptom of spending that has not changed, a longer consolidation term lowers the monthly payment while raising the total cost, and the cause is still there.
What This Calculator Does Not Model
The figures assume a fixed rate for the whole term, no fees inside the balance, and every payment made on time. They exclude payment protection insurance, late payment fees, and any rate change on a variable loan. They also exclude the effect of a missed payment, which on most unsecured loans triggers a fee and a higher rate on the arrears. Where any of those apply, the real cost is higher than the table shows, and the lender's own illustration is the document to check before signing.
Related tools
- Auto Loan Calculator - the same arithmetic with a vehicle as the asset
- Mortgage Calculator - the long-term version, with a repayment ladder by rate and term
- Amortization Calculator - the month-by-month split of every payment
- Interest Calculator - simple and compound interest on a balance you control
- Debt Payoff Calculator - compare avalanche and snowball against a fixed loan
References
- Investopedia, "Amortization" (the annuity payment formula and the interest-to-principal split). https://www.investopedia.com/terms/a/amortization.asp. Accessed 2026-09-27.
- Investopedia, "Annual Percentage Rate (APR)". https://www.investopedia.com/terms/a/apr.asp. Accessed 2026-09-27.
- Federal Deposit Insurance Corporation, "Consumer Resource Center" (loan costs and borrowing guidance). Federal Deposit Insurance Corporation (U.S.), Consumer Resource Center. Accessed 2026-09-27.
- Financial Conduct Authority, "Consumers" (how loans and representative rates are advertised in the United Kingdom). https://www.fca.org.uk/consumers. Accessed 2026-09-27.